Hong Kong Corporate Actions: Placings, Rights Issues, Dividends and More
Disclaimer: For educational purposes only, not investment advice. You are responsible for your investment decisions.
Hawai (Fxcns.com) is not liable for any resulting losses.
A change in the number of shares in your Hong Kong stock account, or a sharp adjustment in a share price, does not necessarily mean an equivalent investment gain or loss. It may reflect fundraising, a distribution or a change in the company's share capital. This guide uses simple examples to explain how placings, rights issues, bonus issues, dividends, share splits and consolidations affect your share count, cash and ownership percentage. All figures are illustrative. Theoretical prices assume other conditions remain unchanged and are not actual execution prices. Rules checked: 24 September 2026.
1. Placings and rights issues: who can subscribe?
In Hong Kong, a placing generally offers shares to selected investors rather than inviting all existing shareholders to subscribe in proportion to their holdings. A rights issue offers eligible existing shareholders the opportunity to subscribe for new shares in proportion to their holdings. Both raise funds, but ordinary shareholders do not have the same opportunity to participate. See the Hong Kong Investor and Financial Education Council's explanations of placings and rights issues. The example below shows how a rights issue works.
Key features of rights issues
- The subscription price is usually below the market price, but a discount does not guarantee a profit
- Eligible shareholders can choose whether to subscribe; if the rights are tradable, they can also sell them under the relevant arrangements
- Shareholders who do not subscribe may see their ownership percentage diluted when new shares are issued; the share price may also change because of the ex-rights adjustment and the market's reaction
Example
Suppose Company A offers three new shares for every 10 shares held, at a subscription price of HK$8.00 per share. The market price before the rights issue is HK$10.
If you are an eligible shareholder holding 1,000 shares, you can subscribe for 300 new shares. The subscription payment is 300 × HK$8.00 = HK$2,400.00 excluding any broker fees. After completing the subscription and receiving the new shares, you will hold 1,300 shares.
A price below the previous market price does not automatically make the investment good value. Before deciding whether to participate, consider:
- Do you have the additional cash, and do you want to increase your investment in this company?
- What will your ownership percentage be after the issue, how will the ex-rights adjustment affect you, and how can you deal with the rights?
- Why is the company raising funds, and how will it use the money? Do its business prospects justify investing more?
Points to check
- Read the announcement to establish whether it is a placing or a rights issue, and whether you are eligible to subscribe
- Assess the use of proceeds and subscription terms rather than focusing only on the discount
- Check the rights trading period and your broker's subscription deadline, and consider your available funds before deciding
2. Bonus issues: more shares do not mean more wealth
A bonus issue distributes additional shares to existing shareholders in proportion to their holdings, usually by capitalising reserves. Shareholders do not pay a subscription price, but issuing the additional shares does not itself bring new money into the company. HKEX's guidance on price adjustments for corporate actions explains the treatment of reference prices for bonus issues and other events.
Key features of bonus issues
- No subscription payment is required, although your broker may charge handling fees
- With other conditions unchanged, the bonus issue itself increases neither the company's market capitalisation nor the total value of your shares
- The theoretical price per share adjusts as the share count rises; the actual market price is still determined by trading
Example
Suppose Company B announces two bonus shares for every 10 shares held.
If you hold 1,000 shares, you will hold 1,200 after receiving the bonus shares. All else being equal, the theoretical price per share becomes approximately 83.33% of its previous level, a decrease of around 16.67% (10 ÷ 12 ≈ 0.8333). The increase in shares offsets the per-share price adjustment; it is not a free 20% gain.
Points to check
- Look at both your share count and total holding value rather than treating bonus shares as an investment return in themselves
- Review the company's business and finances, along with the dates when the bonus shares will be credited and start trading
- Check broker charges and applicable tax treatment instead of assuming there are no costs
3. Dividends: understand the ex-dividend adjustment
This section focuses on cash dividends. Companies usually pay them out of profits, but the announcement will explain the source of the payment and how it will be distributed. To determine your entitlement, pay attention to the ex-dividend date, record date and payment date. Under HKEX's Guide on Dividends and Other Entitlements, buying on or after the ex-dividend date generally does not entitle you to that dividend.
Key features of dividends
- You receive a cash distribution, but fees, taxes or currency conversion may affect the amount credited
- Assess dividend policy alongside earnings, cash flow and funding needs; a large dividend does not necessarily indicate a healthy business
- All else being equal, the theoretical reference price is reduced by the dividend per share on the ex-dividend date; the actual traded price may not move by the same amount
Example
Suppose Company C announces a dividend of HK$0.50 per share, with a share price before the ex-dividend date of HK$20.
If you hold 1,000 shares and qualify for this dividend, your entitlement is HK$500.00 before any applicable taxes and fees. Ignoring other factors, the theoretical ex-dividend price is HK$20.00 − HK$0.50 = HK$19.50 per share. This is an illustrative calculation, not a guarantee that the stock will trade at HK$19.5. The dividend is normally credited according to the announced payment arrangements, not immediately on the ex-dividend date.
Points to check
- Distinguish dividend yield from the dividend payout ratio, and use earnings and cash flow to assess sustainability
- Check the ex-dividend, record and payment dates before deciding how to use the proceeds
- Understand your applicable tax treatment and broker charges, and compare the amount actually credited
4. Share splits and consolidations: share count and price adjust together
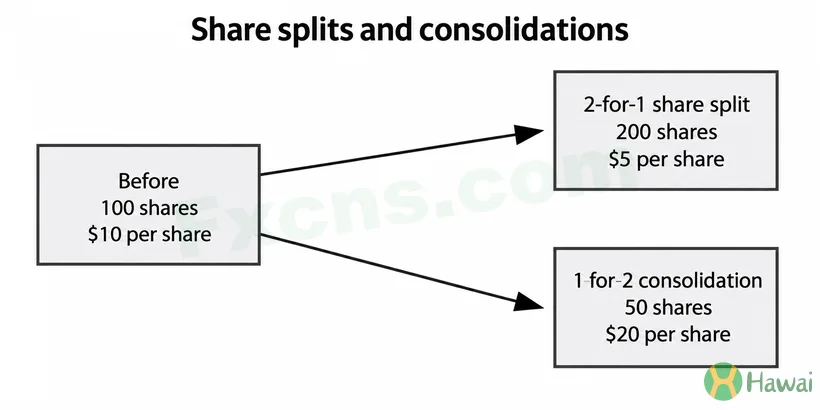
A share split divides one share into several, while a consolidation combines several shares into one. These actions change the number of shares and the stake each share represents, without changing the value of the underlying business in themselves. For reference-price adjustments, see HKEX's trading mechanism and corporate action guidance.
Key features of splits and consolidations
- With other conditions unchanged, the company's market capitalisation and the total value of your shares theoretically stay the same
- They may affect ease of trading, liquidity and investor perceptions, but improved trading activity is not guaranteed
- Check the company's stated reasons; a split or consolidation alone tells you little about the company's prospects
Example
Suppose Company D announces a two-for-one share split.
If you hold 1,000 shares worth HK$50.00 each before the split, you will hold 2,000 shares with a theoretical value of HK$25.00 each afterwards. The holding is still worth HK$50.00,000. Conversely, a two-for-one share consolidation would turn 2,000 shares worth HK$25.00 each into 1,000 shares with a theoretical value of HK$50.00 each. Both calculations ignore market movements and fees.
Points to check
- Check the share count, per-share price and total holding value together; a higher price after consolidation is not an investment gain in itself
- Review the effective date, board lot size, odd-lot treatment and share certificate exchange arrangements, and monitor liquidity changes
- Consider the company's fundraising, business position and announcement to understand the purpose of the split or consolidation
5. What to check before taking action
For any corporate action, first identify whether it changes your share count, cash, ownership percentage or several of these. More shares do not necessarily mean a profit, and a lower share price does not necessarily mean an equivalent actual loss. When reading an announcement, focus on the following:
- Identify the action: Distinguish placings, rights issues, bonus issues, cash dividends, splits and consolidations. Establish what you will receive and whether you need to pay.
- Check total value: Consider shares, cash and related rights together, and distinguish theoretical adjustments from actual market-price changes.
- Watch deadlines: Check eligibility, the rights trading period, subscription deadlines and broker processing times so you do not miss instructions you need to submit.
- Calculate costs: Check broker fees and applicable taxes. Consult a qualified professional about decisions involving your personal tax situation.
- Assess the company: Consider the use of proceeds, earnings and cash flow rather than deciding solely on a discount, bonus ratio or dividend amount.
The company's announcement and your broker's notices govern the specific arrangements. HKEX's common nominee services overview describes the general process for distributing dividends, bonus shares and other entitlements through the settlement system. Ask your broker when the cash or shares will reach your account and when you need to submit any instructions.
Before acting, check three things: how much cash you must contribute or expect to receive, how many shares you will hold afterwards, and whether your ownership percentage changes. Then check the dates and fees. This makes account changes easier to understand and helps you avoid making trading decisions based on a misunderstanding of the corporate action.